

7 Mistakes to Avoid When Building an Emergency Fund From Scratch
Starting an emergency fund may seem overwhelming, especially if you have not set aside any savings yet. Setting up a financial cushion offers peace of mind, helping you...
Aug 22, 2026


Understanding where your money goes for health care starts with tracking every cost, from routine doctor appointments and prescription pickups to unexpected treatments or procedures. By writing down each out-of-pocket payment, you gain a clearer sense of your overall spending habits. Reviewing this list can reveal trends in your medical expenses and point out areas where you might reduce costs. With a full picture of your current and past health spending, you can plan more confidently for future medical needs and set realistic goals that support both your well-being and your budget.
Once you’ve mapped your spending, set concrete goals. You might aim to lower your annual pharmacy bill or trim how much you pay in co-pays for specialist visits. When you know where each dollar goes, deciding where to cut becomes much easier.
Start by gathering every recent medical bill, insurance statement, and prescription receipt. Group them by category: doctor visits, lab tests, imaging scans, medications, and emergency care. This gives you a clear breakdown of where most of your money goes.
Next, track these costs over a three- to six-month period. Use tools like simple spreadsheets or free apps to help you spot high spikes in spending. With data in hand, identify which services cost the most and explore cheaper options.
Compare these factors side by side to choose a plan that suits your needs. Don’t just pick the one with the lowest premium; consider what you might pay if you need multiple services.
After you receive a bill, don’t pay immediately. Check for errors like duplicate charges, incorrect service codes, or visits not covered by your insurance. A single mistake can add a hundred dollars or more to your total.
Implementing these methods immediately can help you save noticeably. For example, asking and agreeing on an installment plan might cut a major hospital bill in half.
Organize your expenses and schedule payments to avoid surprises and late fees. Seeing a clear monthly figure for healthcare helps you keep your budget balanced.
Use free preventive checkups to cut long-term costs. Annual physicals, blood pressure screenings, and certain vaccines usually come at no extra charge with most plans. Early detection prevents minor issues from turning into costly treatments.
Many employers and health plans now offer wellness credits or discounts for gym memberships, smoking cessation classes, and nutrition counseling. These programs often reward you with gift cards or lower premiums if you meet simple activity goals.
Regular exercise, a balanced diet, and managing stress lead to fewer sick days and less medical care over time. Small lifestyle changes can lower your future bills by keeping you healthier today.
Track your spending, select appropriate insurance, and negotiate bills to manage medical costs effectively. Begin today to simplify healthcare expenses and protect your financial health.
Starting an emergency fund may seem overwhelming, especially if you have not set aside any savings yet. Setting up a financial cushion offers peace of mind, helping you...
Aug 22, 2026
Building a lasting legacy begins with careful planning and deliberate action. By deciding how your assets will pass to those you care about, you ensure your wishes...
Jun 15, 2026

Finding harmony between career demands, family responsibilities, and personal well-being often seems challenging. Many people strive to excel at work while maintaining...
Aug 05, 2026
Managing rent, car payments, and student loans while balancing a side hustle and freelance work often feels overwhelming. Breaking down each income stream and...
Jun 10, 2026
Buying property often feels confusing at first, especially when you are unsure of the steps involved. You may find yourself asking which actions to take or how to...
Jul 24, 2026

Building healthy habits around substance use calls for steady commitment and simple, everyday actions. By selecting positive alternatives and creating routines that...
Sep 04, 2026
Many people experience quiet moments of loneliness that can settle into daily routines, making even ordinary activities feel less fulfilling. Small choices, like...
Jun 28, 2026
Many people who change careers in midlife encounter unique challenges along with the opportunity to redefine their financial future. It helps to look closely at how your...
Sep 21, 2026
Many people find the process of preparing for retirement complex and overwhelming. Annuities offer a reliable way to create financial security during your later years....
Jun 21, 2026

Life often brings significant changes, such as relocating, starting a different job, or navigating health issues, that can unsettle daily routines. Facing these...
Aug 09, 2026
Finding time for a passion project while managing a busy job requires careful organization, yet every step forward brings a sense of satisfaction. People often balance...
Jun 06, 2026
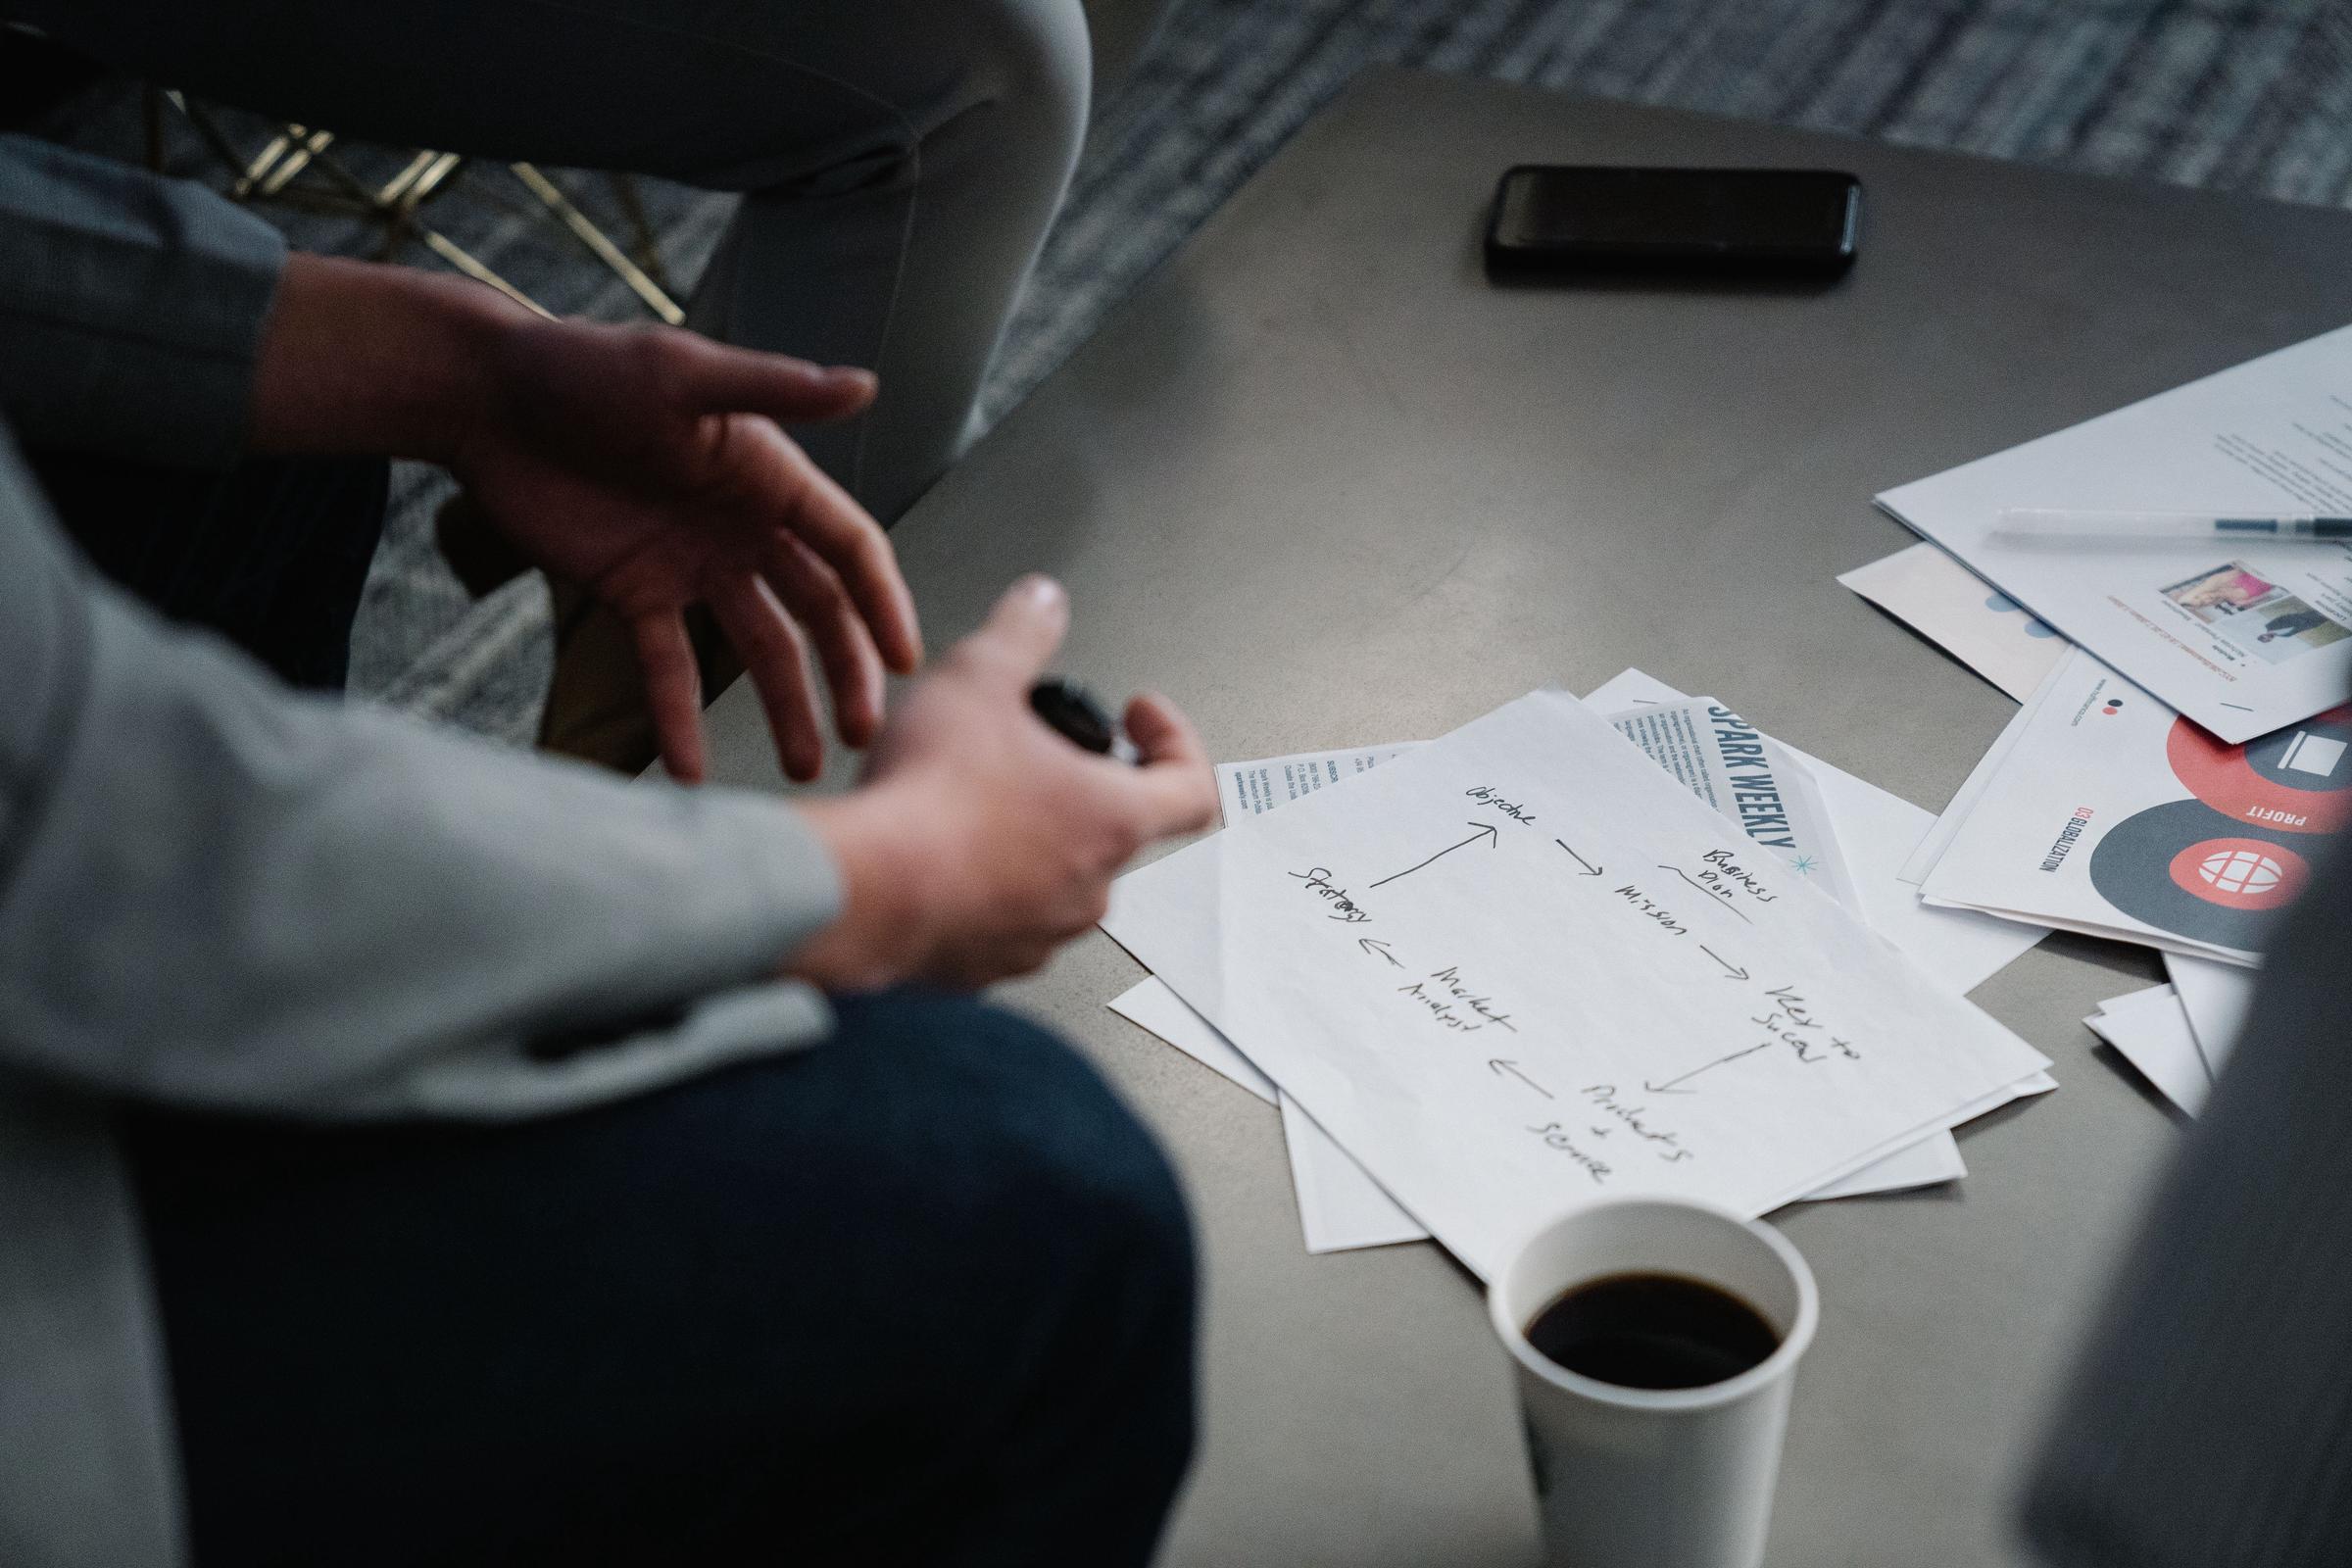
Building a strong succession plan ensures that valuable knowledge passes seamlessly from today’s leaders to tomorrow’s. Teams that prepare in advance for transitions...
Jul 15, 2026

Strong succession planning relies on preparing small teams for seamless changes in leadership. Leaders create a solid foundation by setting clear objectives and...
Aug 19, 2026
Feeling comfortable and secure in your own skin remains important, no matter how life unfolds or what the mirror shows. Changes in appearance are natural, but shifting...
Aug 02, 2026